calculate cost of sheet metal parts
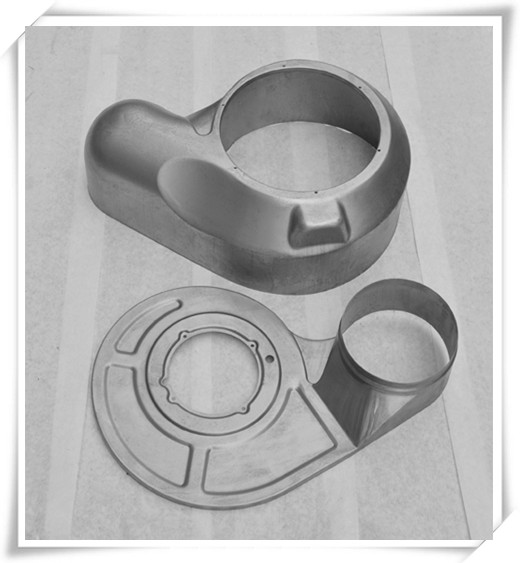
Absence of clearness in the expenses of sheet metal parts
The production of sheet metal parts is important in various commercial treatments. Nonetheless, what might seem simple sheet metal items regularly conceal a complex variety of costs that are not easily evident. As a result, comprehending the costings can be rather hard, especially when it includes accounting for concealed expenses within the part itself and throughout the whole worth generation procedure.
The production of sheet metal parts is important in various commercial treatments. Nonetheless, what might seem simple sheet metal items regularly conceal a complex variety of costs that are not easily evident. As a result, comprehending the costings can be rather hard, especially when it includes accounting for concealed expenses within the part itself and throughout the whole worth generation procedure.
In this analysis, we check out the widespread problems of expense opaqueness and their repercussions for organizations in the sheet metal processing sector, together with prospective solutions.
The expense openness of sheet metal parts is significantly impacted by the modifications in product costs. Business that style and produce these parts frequently deal with unforeseeable variations in the rates of basic materials, making it challenging to properly determine expenses. When providers do not supply clear rates structures, it can develop monetary unpredictability and substantially effect the job's general expense.
One possible resolution is to develop prolonged agreements with providers and use innovation for real-time tracking of product costs, which can boost expense management and boost openness.
Throughout the item advancement phase, around 70% of the general expense of an item is currently developed. If there are inaccurate expense estimates and an absence of standardization in products, producing procedures, and other aspects, it can lead to going beyond the spending plan. Moreover, inadequate interaction amongst various departments such as advancement, production, and acquiring can cause misconceptions and inaccurate presumptions.
Possible resolution: Through the usage of automatic expenditure calculations, designers have the capability to discover possible expense influencers throughout the preliminary phases of item advancement. This enables the recognition of private expenditure elements, consisting of products, waste, and production strategies such as laser cutting, sheet metal flexing, and welding. By doing so, chances for expense optimization can be executed right from the beginning of the sheet metal production procedure. As a result, parts can be produced with approximately a 20-30% boost in expense performance due to create improvements. In addition, the choice of products and production approaches likewise affect the general costs related to the part.
Hidden costs can develop throughout the production procedure of sheet metal parts, which might not be right away obvious. These expenditures incorporate different elements such as specialized tools, the time needed for establishing, and quality control procedures. Stopping working to take these elements into account can lead to a considerable increase in general expenses.
Alternative option: Conducting an extensive evaluation of making treatments, determining locations for enhancing, and executing advanced production tools can assist to minimizing hidden production costs.
Disparities amongst departments
When numerous departments within a company absence accurate knowledge relating to the costs connected with sheet metal parts, it can hamper functional efficiency. Choices might be made without acquiring extensive details. As a result, there is a requirement for much better coordination amongst departments such as acquiring, production, managing, and quality assurance, which can lead to greater administrative work and less effective procedures.
When numerous departments within a company absence accurate knowledge relating to the costs connected with sheet metal parts, it can hamper functional efficiency. Choices might be made without acquiring extensive details. As a result, there is a requirement for much better coordination amongst departments such as acquiring, production, managing, and quality assurance, which can lead to greater administrative work and less effective procedures.
One prospective method to resolve these troubles is by boosting interaction in between various groups, embracing transparent techniques to examine expenses, and making use of innovation for effective information sharing. For example, presenting a universal estimation tool that can be made use of by all departments would use a holistic understanding of the expense elements related to sheet metal parts.
The opaqueness of costs can likewise impact the motion and coordination of sheet metal parts, triggering uncertainty in shipping charges, customizeds charges, and shipment timelines. This can substantially affect the overall task expenditures, causing unanticipated and unwanted boost.
One possible resolution might include working together with credible transport and logistics partners who offer transparent prices designs. This technique can add to improving exposure within the transport and logistics sector.
In summary, companies that produce sheet metal parts frequently come across the challenge of nontransparent rates. To conquer this obstacle and keep long-lasting competitiveness, it is vital to acknowledge and deal with the elements that add to these expenses. By teaming up with reputable providers, leveraging sophisticated innovation, and completely analyzing production approaches, companies can minimize concealed expenditures and increase openness. The execution of a thorough computation tool for sheet metal parts is not simply a software application financial investment; it is a tactical choice to improve expense presence, performance, and interdepartmental cooperation. This tool makes it possible for business to decrease job expenses and enhance their whole worth chain.